Snowball vs avalanche method calculator
Two ways to order the same payments. Type your debts and an extra amount to see months to debt-free and interest paid for each, side by side.
Avalanche puts the extra money on the highest interest rate first. Snowball puts it on the smallest balance first. The calculator runs both on your debts and shows what the arithmetic gives. In the example further down the difference is $82 of interest; with other debts it can be nothing at all.
Your debts
The calculator needs JavaScript on this page. An example is worked out below.
Use the balance, APR and monthly payment from your statements. The numbers in the boxes are an example. A full month-by-month schedule, as a table, a CSV file or a printout, is on the debt payoff calculator. The same two orders are in a spreadsheet, and the rules for choosing between them are on a printable sheet.
What each method is
Avalanche (highest rate first). Every debt gets its scheduled payment. The money left over — your extra amount, plus the payment of any debt that has been cleared — goes to the debt with the highest interest rate. When that debt is cleared, the one with the next-highest rate takes over.
Snowball (smallest balance first). The same payments, but the money left over goes to the debt with the smallest balance, whatever its rate. When that debt is cleared, the one with the next-smallest balance takes over, and so on.
One worked example
Three debts in which the smallest balance is not the highest rate: a store card of $900 at 12% with a payment of $45, a credit card of $4,200 at 24% with $120, and a car loan of $12,600 at 7.5% with $330. The extra amount is $300 a month.
| Way of paying | Debt-free in | Interest paid |
|---|---|---|
| Scheduled payments only | 61 months | $5,046 |
| Highest rate first (avalanche) | 25 months | $1,871 |
| Smallest balance first (snowball) | 25 months | $1,954 |
On these numbers, highest rate first pays $82 less interest than smallest balance first, and both finish in the same month. The first debt is cleared in month 12 by highest rate first (Credit card) and in month 3 by smallest balance first (Store card).
The order the debts close
Highest rate first
- Credit card month 12
- Store card month 13
- Car loan month 25
Smallest balance first
- Store card month 3
- Credit card month 13
- Car loan month 25
Scheduled payments only
- Store card month 23
- Car loan month 44
- Credit card month 61
Each debt on its own payment: nothing rolls from one to the next.
What the numbers show
Highest rate first pays $82 less in interest here, and both orders finish in 25 months. Smallest balance first clears its first debt, the Store card, in month 3; highest rate first clears its first, the Credit card, in month 12. Which of these matters more is your call: the calculator shows both and does not pick one.
When the two give the same answer
- There is one debt. There is no order to choose.
- The smallest balance is also the highest rate. Both methods then point at the same debts in the same order.
- Every debt has the same rate. The highest-rate order falls back to the smaller balance on a tie, which is the snowball order.
| Debts | Highest rate first | Smallest balance first |
|---|---|---|
| One debt: a credit card of $4,200 at 24% | 12 months · $534 | 12 months · $534 |
| Two debts: a store card of $900 at 29.99% and a car loan of $12,600 at 7.5% | 22 months · $1,004 | 22 months · $1,004 |
| Three debts, all at 18%: $900, $4,200 and $12,600 | 28 months · $4,002 | 28 months · $4,002 |
In each row the two columns are the same. Change one debt's rate or balance and they can part.
How the numbers are counted
Month by month: interest at the APR divided by twelve is added to every open debt, every debt gets its scheduled payment, and the rest goes to the debt the order points at. A balance under 50 cents counts as paid, and a debt still open after 600 months — 50 years — is shown as not paid off, with the reason: the balance falls too slowly, or the payments do not cover the interest. The steps are written out on the debt payoff calculator page. Fees, a rate that changes and a lender's day-by-day interest are not counted, so a lender's own schedule can differ from this one.
Both orders in Pennyjar
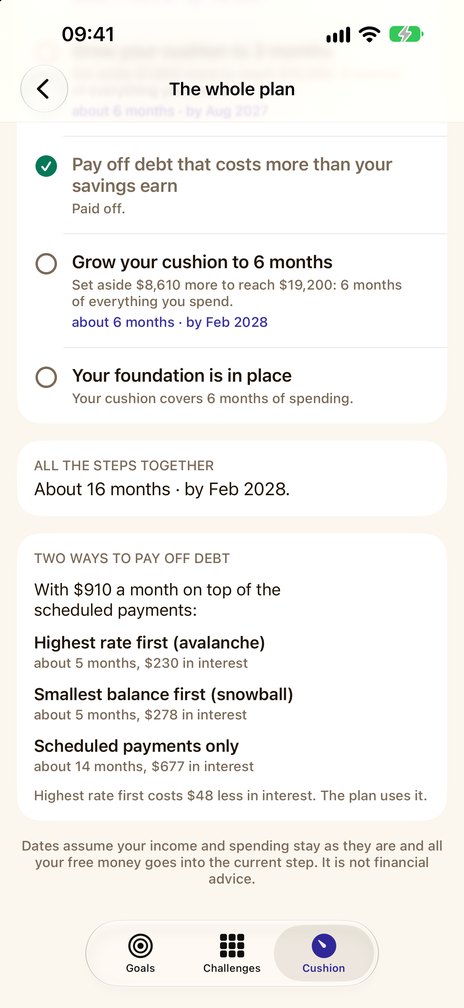
Pennyjar is an iPhone and iPad app with three tabs: Goals, Challenges and Cushion. With Pennyjar Pro (one payment for the whole app, no subscription), two or more debts and money left free each month, avalanche and snowball are compared on your own debts: the comparison appears when at least two debts are in it and some money is left each month. It is part of the Cushion tab, where the whole plan, step by step with dates, is also Pro.
Coming soon to the App Store
More calculators
- Debt payoff calculatorthree ways to pay, month by month
- Which debt first, or save first?the whole ladder for your numbers
- Emergency fund calculatorwhat 1, 3 and 6 months of spending come to
- How long will my savings last?months, and the month the money runs out
- Debt payoff spreadsheetan .xlsx file with the formulas in it
- Printable debt payoff trackera debt list and a payoff log, as PDFs
A calculation from your numbers and the rules on this page. It is not financial advice, and it says nothing about investing.
More free savings tools
Last reviewed 8 October 2026